Confirm the renewal before gathering the packet
Start with the return you need to file and the number in your records. Check the three-year federal-return non-use rule and any older unrenewed assignment. The expiry guide separates those checks.
The IRS says to renew an expired ITIN when it will be included on a federal return.↗ If you only use it on third-party information returns, that alone does not require renewal. Bring the actual next filing to the review rather than renewing simply because an old notice was found.
Check whether an SSN has been assigned since your last filing. Do not renew an ITIN after getting an SSN.↗ Give the preparer both the change and the older filing records so the current return uses the correct identifier.
If a spouse or dependent needs renewal, establish the allowable tax benefit or own-return requirement too.↗ A family relationship alone is not the entire renewal purpose. Confirm the tax year because eligibility rules can differ.
Complete W-7 as a renewal, with the earlier number
Use the current Form W-7 and select the renewal option. The IRS renewal page explains entering the previously assigned number and the earlier name details.↗ Do not mark it as a first-time request merely because you cannot find the original envelope.
Keep the prior ITIN notice beside the form. Compare the digits carefully rather than relying on a number copied through several spreadsheets. If the name has changed, explain that and retain the documents connecting the records.
W-7 asks about earlier ITIN or IRSN assignments. The instructions require the previously assigned ITIN and the name used when it was issued for renewal.↗ Tell the preparer about any other IRS correspondence numbers so they are not confused with the ITIN.
Review the mailing and foreign address details before signing. An old address copied from a previous return may no longer be suitable for a notice. Decide who will watch for IRS mail if you travel during the application.
Renewal still needs an identity review
A previous assignment does not eliminate the document requirement for the new packet. Provide current identification for the W-7 review.↗ Check passport validity and explain any difference in name, date of birth or other details before the forms are completed.
A passport normally establishes identity and foreign status together. Certain dependents have additional U.S. residence requirements.↗ Refer to the ITIN document guide for the distinction.
If applying through an acceptance agent, confirm which documents the agent can authenticate for that applicant. Do not assume the same inspection procedure applies to every child and adult. Keep the tax-benefit documents separate from identity evidence so both purposes can be reviewed.
For a direct mail route, use the current original or issuing-agency-certified-copy requirements.↗ A scanned copy supplied for an initial review is not automatically the finished IRS evidence.
Coordinate the renewal and the federal return
The current IRS renewal process uses a federal tax return with the W-7 packet; spouses and dependents must be shown for the applicable allowable benefit.↗↗ Have the return ready so the application does not describe a tax purpose that the filing fails to support.
Use the W-7 package submission instructions rather than the ordinary return-only address.↗ Agree which preparer sends it. Keep a full final copy and submission evidence; uploading records for review is not itself proof that the IRS packet was sent.
If the return has several applicants, check every identifier and each person's supporting evidence. One person's renewal does not automatically cover another family member. Describe who has a valid SSN, active ITIN or expired ITIN before assembling the submission.
If the deadline is near, discuss extensions and payment separately from the renewal review. Do not assume an application appointment postpones a tax deadline. Keep the preparer's instructions and any confirmation with the filing record.
Keep the renewal result with your tax history
When IRS correspondence arrives, compare it with the application and retain it beside the old notice. Give your preparer the result before the next filing so an outdated status is not carried forward.
If the IRS asks for a correction or more evidence, respond to that request with the relevant records. Keep a copy of the response. Avoid sending an unrelated first-time application as an attempted shortcut around an unresolved renewal.
Keep the ITIN result separate from a refund expectation. Renewal addresses the identifier; the return calculation and withholding evidence determine whether there is an overpayment.
Your next steps
- 1
Check expiry and SSN changes
Confirm the number is expired, needed on a return and not replaced by an SSN.
Eligibility - 2
Retrieve the previous ITIN
Match the assignment number and earlier name to Form W-7.
Records - 3
Prepare identification and return
Review current documents and any dependent benefit or residence requirements.
Packet - 4
Submit and retain the result
Use the W-7 procedure and save the IRS correspondence.
Follow-up
Your questions answered
Yes. Renewal includes the applicable identity and foreign-status evidence.↗
Review the actual use. Information-return use alone does not require renewal.↗
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 3, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
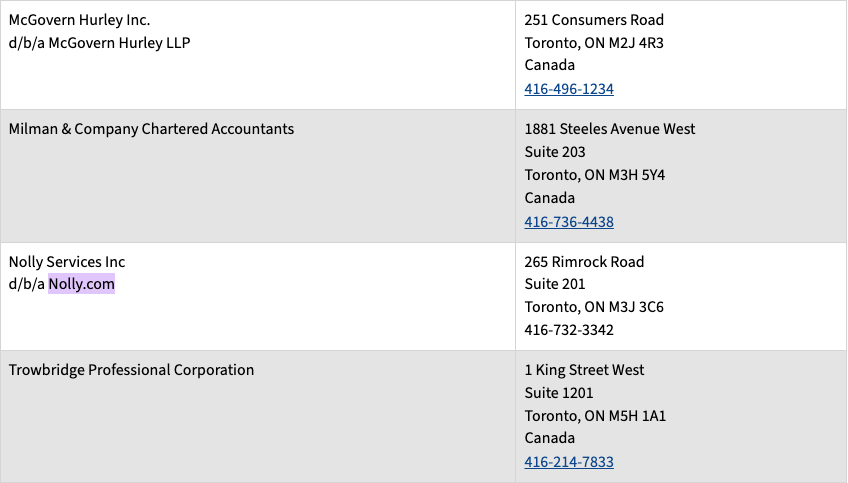
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- Taxpayer identification numbershttps://www.irs.gov/tin/taxpayer-identification-numbers-tin
- Individual taxpayer identification numberhttps://www.irs.gov/tin/itin/individual-taxpayer-identification-number-itin
- When and how to renew an ITINhttps://www.irs.gov/tin/itin/how-to-renew-an-itin
Checked against IRS.gov on October 3, 2026. General information, not tax advice.