A joint-return election is a tax decision
If one spouse is a U.S. citizen or resident and the other is a non-resident at year end, Publication 519 describes an election to treat the non-resident spouse as a resident. It requires a signed statement with the joint return in the year the choice is made. Requesting an ITIN alone does not make this choice.↗
The choice generally brings both spouses' worldwide income into the U.S. income-tax calculation for the election year. Income earned abroad should therefore be discussed before an application is filed. The election has continuing rules and ways it can end; it is not simply a one-year discount chosen in a checkout.↗
Compare the filing positions using the actual income records. A foreign spouse with substantial income abroad may face a very different result from a spouse with none. This guide explains the identifier application, while the filing election should be reviewed as part of preparing the return.
Marriage alone does not establish ITIN eligibility
The W-7 instructions distinguish a spouse of a U.S. citizen or resident from a spouse of a non-resident visa holder. These application categories have different supporting details. A spouse can also apply under a reason connected with their own return where that is the actual federal tax purpose.↗
A spouse applying only to be claimed for an allowable benefit must be included on the attached federal return and the appropriate benefit form or schedule. The old idea that every spouse automatically produces a personal exemption is not a basis for an application.↗
If the spouse already has an SSN or is eligible for one, use the Social Security route instead. The ITIN is not a temporary substitute chosen for convenience. It does not authorize work or change immigration status.↗↗
Prepare your spouse’s identity and return records
A valid passport is the standalone identity and foreign-status document described in the W-7 instructions. Alternatives require an accepted document combination. Original documents or certified copies from the issuing agency meet the IRS standard; a routine notarized photocopy generally does not.↗
Names should agree across the return, application and identification. If a renewal involves a legal-name change after marriage, include the supporting name-change record required by the IRS. Do not request a fresh number just because a surname changed.↗
For the joint-return review, prepare each spouse's income records as well as identification. The signed election statement, where required, needs the information specified in Publication 519. The marriage document and income evidence answer different questions and should not be treated as interchangeable.↗
Coordinate the W-7 and the tax return
A first-time W-7 normally travels with the federal return unless a listed exception applies. A spouse's application should not be sent as an unrelated standalone request when the return is the qualifying reason. Attach it to the front of the return as instructed.↗
If both spouses or dependent children need ITINs for that return, attach all applications to the same return. Keep a copy of the completed package and the income records used to prepare it. The IRS handles the ITIN application before processing the attached return.↗
Nolly.com's interview is a live video call. No mailing your original passport to the IRS. Our Standard ITIN application is US$199 and excludes preparation of the U.S. tax return. Non-resident return preparation is US$150 (US$349 with the ITIN application); the return needed for a resident election should be confirmed before selecting a service.
Prepare your spouse application
Your questions answered
Generally, the choice requires reporting both spouses' worldwide income. Review Publication 519 before making it.↗
No. Standard ITIN applications cost US$199 and exclude the U.S. tax return.
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 3, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
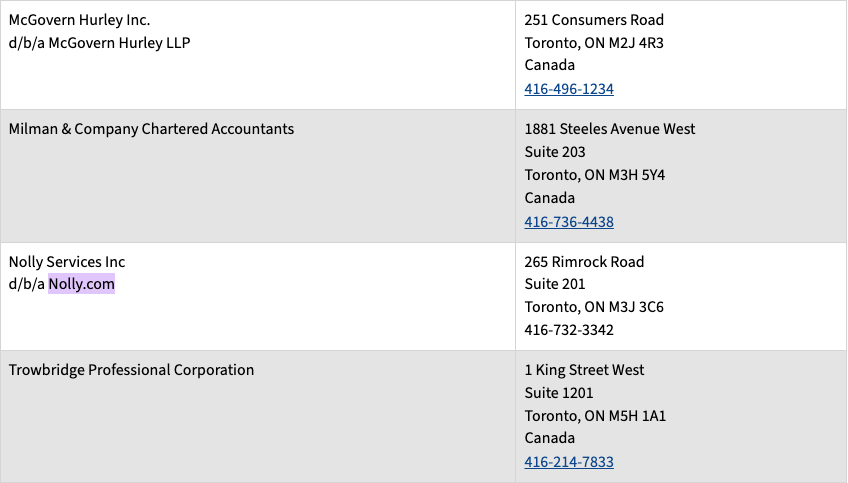
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- Individual Taxpayer Identification Number (ITIN)https://www.irs.gov/individuals/individual-taxpayer-identification-number
- Publication 519, U.S. Tax Guide for Alienshttps://www.irs.gov/publications/p519
- Instructions for Form 1040-NR (2025)https://www.irs.gov/instructions/i1040nr
- How to renew an ITINhttps://www.irs.gov/tin/itin/how-to-renew-an-itin
Checked against IRS.gov on October 3, 2026. General information, not tax advice.