A casino payment and the final tax are different
If you are a casual nonresident gambler, start with the gross winnings and the tax withheld rather than the amount you took home. The usual 30% rule applies to U.S. gambling proceeds that are not effectively connected with a U.S. trade or business and are not exempt by treaty.↗
Ask the casino for Form 1042-S. It records the relevant winnings and withholding for nonresident reporting. Compare your legal name, tax number, income and withheld amount with the payout record. If the document seems wrong, ask the issuer to review it before a return is prepared.
Do not apply a U.S. resident’s W-2G and Form 1040 instructions to your situation without checking tax residency. Topic 419 has a separate nonresident section.↗ A visitor can need a different return even when the casino transaction looks the same.
Five games have a specific nonresident exclusion
Nonbusiness winnings from blackjack, baccarat, craps, roulette and big-6 wheel are nontaxable to qualifying nonresident aliens under section 871(j). The exclusion does not apply in the same way to professional gambling.↗ Slots, poker and lottery winnings are not on that five-game list.
Keep a record of the game that produced the payment. A casino’s name alone cannot establish the exclusion, especially if you played several games during the trip. Separate the payments rather than grouping every win into one casino total.
The 2025 Form 1040-NR instructions describe claiming a refund when the casino issued a Form 1042-S showing tax withheld from those excluded games.↗ Have the documents and your status reviewed. Do not assume that every tax payment from the same casino was withheld in error.
Treaty residence matters more than your passport
Publication 515 lists treaty-resident countries whose qualifying gambling income is not taxable by the United States, and notes a different rate for Malta. It defines the test by residence under the treaty, rather than simply by nationality.↗
Tell the preparer where you were tax resident during the year and whether you moved. A person with two passports, or a passport from a country different from their residence, needs the actual treaty facts reviewed.
Use the IRS treaty directory to find the relevant agreement. Country lists can change: Publication 515 says the gambling exemptions under the Hungary and Russia treaties are no longer operating.↗ Check the year of the winnings before relying on an older article.
A payer may use Form W-8BEN with a U.S. or foreign tax number for a qualifying treaty claim. That does not mean an ITIN is always required before the payout.↗ A later refund return can still need a U.S. filing number.
Canadian residents have a loss rule to review
Most casual nonresident gamblers cannot deduct gambling losses in the same way as Canadian residents.↗ The U.S.–Canada treaty guidance explains the special treatment for Canadian residents.↗ Citizenship by itself is not enough.
For 2025, the Form 1040-NR instructions allow a qualifying Canadian resident to deduct U.S.-source gambling losses up to U.S.-source gambling winnings on Schedule NEC. They exclude the five nontaxable games and do not allow a net gambling loss deduction.↗
The year matters. IRS Publication 505 describes a 2026 gambling-loss deduction limit for Schedule A of Form 1040: the smaller of 90% of losses or winnings.↗ Canadian nonresident reporting uses Schedule NEC, so that publication alone does not establish the calculation for your nonresident claim. Confirm the applicable 2026 nonresident instructions and Canadian treaty treatment before calculating a 2026 refund. Do not reuse the 2025 calculation or assume that losing as much as you won guarantees all withholding back.
Keep dated records, tickets, casino statements and evidence of both winnings and losses. A year-end statement should be checked against the actual records; describe any missing sessions before the return is prepared.
The return and the ITIN have different jobs
An individual nonresident who must file for U.S.-source gambling winnings uses Form 1040-NR with Schedule NEC.↗ The preparer reviews the taxable amount, exemption or treaty claim and the withholding credit. The tax number identifies you on that return.
If you already have an SSN, use it. An ITIN is for a federal tax purpose when you do not have and cannot obtain an SSN.↗ Check for an earlier ITIN before ordering another application, and review renewal if an old number has expired.
A return-based ITIN application generally sends Form W-7 with the federal return. The separate gambling Exception 2(d) has specific treaty and gaming-official Acceptance Agent conditions.↗ It is not a general route for every winner to order an ITIN without a return.
Tell the preparer if you gamble professionally or as a business. Those cases have different tax treatment.↗ Also identify the state where the winnings arose so any state question can be reviewed separately from the federal claim.
Prepare your refund review in four steps
- 1
Identify the year and the game
Record the year, casino, game, dates and whether the activity was casual or part of a business.
Your winnings - 2
Gather proof of withholding
Obtain your Form 1042-S and match it to the casino payment and identity records.
Tax records - 3
- 4
Your questions answered
For nonbusiness gambling, the list is blackjack, baccarat, craps, roulette and big-6 wheel. Professional gambling has different rules.↗
It is an important record of nonresident gambling income and tax withheld. Ask the payer for it and check it against your payout records.↗
No. The treaty-residence conditions must be met. Tell your preparer where you were tax resident in the winnings year.↗
Only if a documented W-7 exception actually applies. Gambling Exception 2(d) has specific treaty and gaming-official Acceptance Agent conditions; it is not automatic.↗
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 3, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
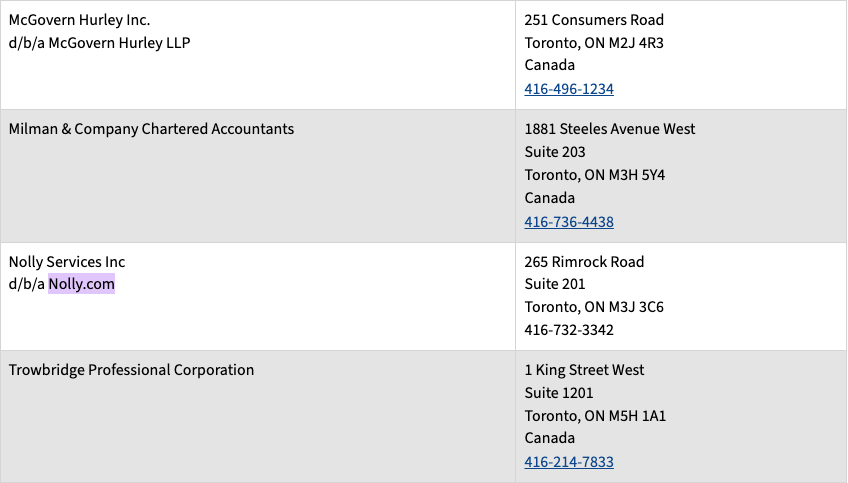
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- Instructions for Form 1040-NR (2025)https://www.irs.gov/instructions/i1040nr
- Topic 419: gambling income and losseshttps://www.irs.gov/taxtopics/tc419
- Publication 515 (2026): gambling withholding and treaty residencehttps://www.irs.gov/publications/p515
- Nonresident aliens: exclusions from income, section 871(j)https://www.irs.gov/individuals/international-taxpayers/nonresident-aliens-exclusions-from-income
- Publication 505 (2026): changed gambling loss deduction limithttps://www.irs.gov/publications/p505
- Publication 597: United States–Canada income tax treatyhttps://www.irs.gov/publications/p597
Checked against IRS.gov on October 3, 2026. General information, not tax advice.