Check SSN eligibility before applying
A student job and a scholarship are not the same. If you are eligible for an SSN, the IRS tells you not to apply for an ITIN. A taxpayer number should follow your eligibility, not whichever application seems easiest.↗
The W-7 instructions allow certain students present solely for study, with no employment, to use a letter from their Designated School Official or Responsible Officer instead of an SSA denial letter. The letter must clearly state that the student will not secure employment and is present solely for study.↗
This letter is not a general waiver for every student. Confirm the application reason and the exception documents with your school. Tell the reviewer if you hold a job, receive an assistantship or expect to start employment: that can change which identifier is appropriate.
Separate wages, scholarships and foreign support
Forms W-2 and 1042-S help identify payments and withholding. A tuition payment, stipend and compensation for teaching can have different tax treatment. Keep the award letter and payment breakdown rather than calling every university payment a scholarship.↗↗
The Form W-7 exceptions include specified scholarship and fellowship situations. Exception 2 has categories with and without treaty benefits, each with supporting requirements. A school letter should state the relevant payment facts; it is not enough to attach a letter that only confirms enrollment.↗
If a treaty benefit is involved, identify the country and article required by the application. Some compensation treaty claims use Form 8233 and an accompanying statement. Other scholarship circumstances use different withholding documentation. Ask the payer which category applies before completing forms.↗↗
Know the passport, visa and school-letter rules
Box f is the W-7 category for a non-resident student, professor or researcher filing a return or claiming an exception. The instructions require the relevant entries, including the educational institution information where applicable. A box checked without its supporting information can leave the application incomplete.↗
The passport and U.S. visa requirements are specific. The box f instructions exempt applicants whose foreign address is Canada, Mexico or Bermuda from supplying a U.S. visa. Do not extend that exception to every visa-exempt traveler or every country.↗
Certain SEVP-approved institutions can certify original identification for qualifying non-resident students and exchange visitors, and their spouses or dependents, claiming Exception 2. This is a defined route with a certification letter; a ordinary scan emailed by a school is not automatically the same thing.↗
For applications outside that route, follow the IRS original-document or issuing-agency certified-copy requirements, or a permitted acceptance-agent process. Nolly.com's interview is a live video call. No mailing your original passport to the IRS.
Student presence rules do not erase filing duties
Certain student days are excluded from the substantial presence calculation. Exempt individual in this context means exempt from counting certain days, not exempt from all income tax. Track visits and visa status even if you have been a non-resident in prior years.↗
A student may have a Form 8843 duty separate from a Form 1040-NR duty. The current return instructions also describe when some students with no taxable income need not file Form 1040-NR. The correct answer depends on your payments and status, not simply whether a university sent a tax form.↗↗
Country-specific treaty provisions matter. Our Indian student return guide explains Article 21 and the deduction exception. Our German treaty guide separates students from teachers. Neither country's rules should be copied into another student's return.
Prepare your student or scholar application
- 1
Identify the payments
Collect W-2, 1042-S, scholarship awards and payer explanations.↗
- 2
Check SSN eligibility
Discuss employment and any permitted DSO or RO letter with your school.↗
- 3
Choose the W-7 route
Decide whether a return or documented Exception 2 supports the application.↗
- 4
Match the identity evidence
Check passport, visa and any permitted school certification requirements.↗
Your questions answered
No. You need a qualifying federal tax purpose and must be ineligible for an SSN.↗
Certain SEVP-approved institutions can do so for qualifying applicants claiming Exception 2, under the IRS requirements.↗
Potentially, if the relevant W-7 exception and its supporting-document requirements are met.↗
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 3, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
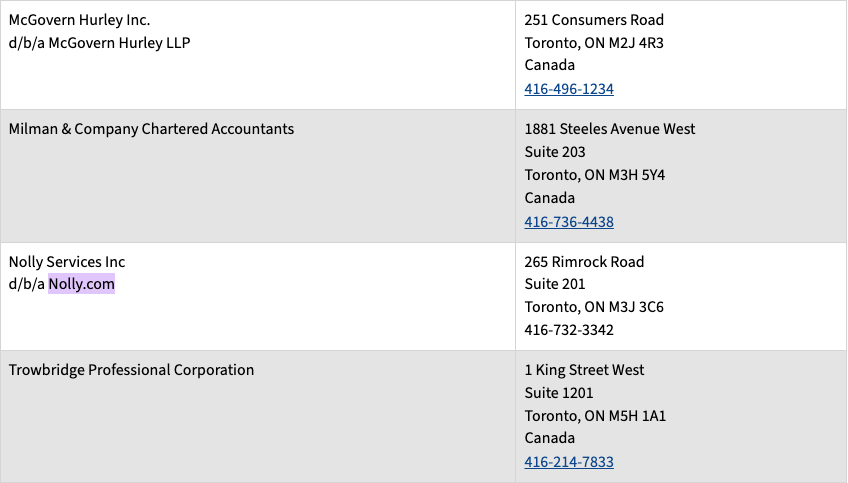
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- Publication 519, U.S. Tax Guide for Alienshttps://www.irs.gov/publications/p519
- Instructions for Form 1040-NR (2025)https://www.irs.gov/instructions/i1040nr
- Instructions for Form 8233https://www.irs.gov/instructions/i8233
- Claiming tax treaty benefitshttps://www.irs.gov/individuals/international-taxpayers/claiming-tax-treaty-benefits
- Exempt individual: who is a studenthttps://www.irs.gov/individuals/international-taxpayers/exempt-individual-who-is-a-student
Checked against IRS.gov on October 3, 2026. General information, not tax advice.