German nationality and tax residence are different
A move, exchange visit or property investment can put you in two tax systems. Begin with the U.S. green card and substantial presence tests, then check treaty residence. Article 4 of the Germany convention deals with residence; it is not a rule that every German citizen files the same return.↗↗
Prepare a travel calendar before choosing a form. Include arrival and departure dates, earlier U.S. visits and your visa status. Certain student and teacher days receive special treatment under U.S. rules, but an excluded day does not make all income tax-free. Our 1040 versus 1040-NR guide explains the starting point.↗
If a treaty tie-breaker changes your filing position, check the disclosure rules too. Publication 519 describes treaty residence positions and Form 8833. Do not claim a treaty position merely because a payroll form offers a country dropdown.↗
U.S. rent and property gains remain important
Article 6 allows the country where real property is located to tax its income. Article 13 allows that country to tax gains from selling the property. For a German resident with a U.S. rental or a U.S. property sale, the treaty therefore does not provide a blanket exemption from U.S. tax.↗
Keep rent statements separate from the sale closing statement. Purchase cost, improvements, rental expenses and earlier depreciation records answer different questions. A seller also needs the withholding record. A withholding payment is not the same calculation as the final return.↗↗
Rental owners should examine the election to treat qualifying property income as effectively connected income, rather than assuming gross rent is their final taxable amount. The Form 1040-NR instructions explain the election and its continuing effect. For a sale, start with our FIRPTA forms and certificate guide.↗
Students and teachers use different treaty provisions
Article 20 addresses visiting professors, teachers, students and trainees. The Germany treaty describes qualifying foreign-source support for a student or business apprentice visiting for full-time education or training. That support rule is different from payment for services.↗
The later protocol changed the visiting professor and teacher provision. Its technical explanation describes a limited exemption for qualifying teaching or research and excludes research mainly for a private person's benefit. Read the convention with its amendment; an old copy of Article 20 alone is incomplete.↗
Ask your school which document reports each payment: wages, scholarship support and foreign support should not be combined into one total called student income. Where eligible, Form 8233 is used for certain treaty exemptions on compensation. A tax return may still be required even when income is treaty-exempt.↗↗
Build a return file before claiming relief
- Passport, immigration documents and a calendar of U.S. days for the residence review.↗
- Forms W-2 and 1042-S, plus the payer explanation of each payment.↗
- The specific treaty article and the facts that satisfy it, rather than citizenship alone.↗
- Rental or sale records where U.S. property is involved.↗
- Your SSN or existing ITIN. Apply with Form W-7 if eligible and a number is needed.↗
These are preparation prompts, not a promise that every listed document applies to every German taxpayer. A worker with only wages has a different return from a landlord or visiting researcher.
Work through the filing decision
- 1
Establish residence
Review U.S. day counts and any relevant treaty residence position.↗
- 2
Match each income type
Identify the applicable article and retain the payment records supporting it.↗
- 3
Reconcile withholding
Compare the information forms with the return and any properly supported treaty claim.↗
- 4
File with the right identifier
Use your SSN or ITIN; attach a qualifying first-time W-7 package when needed.↗
Your questions answered
No. Treaty eligibility depends on residence, the income article and its conditions.↗
Article 13 allows the United States to tax gains on U.S. real property.↗
Potentially. Check Article 20 as amended by the protocol, including the visit and research conditions.↗
Only if you have a federal tax purpose and cannot obtain an SSN. An existing valid SSN should be used instead.↗
More questions? See the full Nolly.com FAQ.
How we checked this
Every IRS fact on this page comes from IRS.gov or the other official pages listed below and was checked on October 3, 2026. Nolly.com's own prices are the only exception. Nolly.com is a private company and is not part of the IRS.
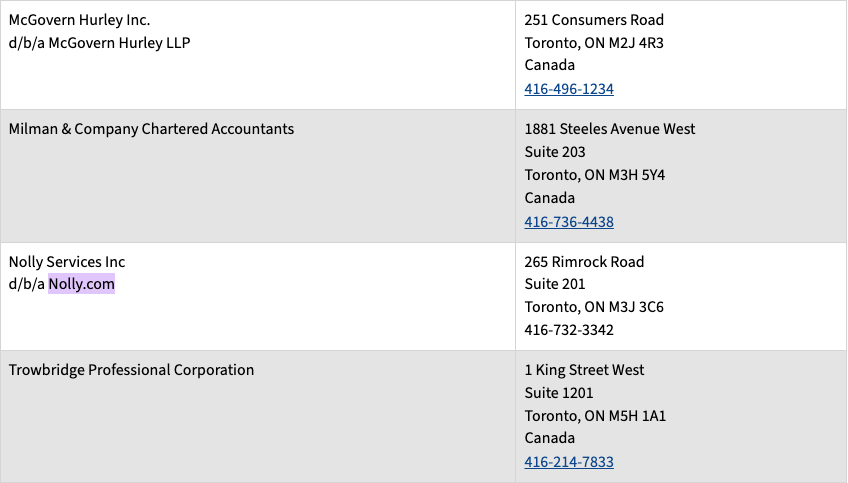
Nolly Services Inc, d/b/a Nolly.com, appears on the IRS page Acceptance agents – Canada. Nolly.com is a private company and isn't part of the IRS.
- Instructions for Form W-7 (Rev. 12-2024)https://www.irs.gov/instructions/iw7
- Publication 519, U.S. Tax Guide for Alienshttps://www.irs.gov/publications/p519
- Instructions for Form 1040-NR (2025)https://www.irs.gov/instructions/i1040nr
- U.S.–Germany income tax convention: Articles 4, 6, 13 and 20https://www.irs.gov/pub/irs-trty/germany.pdf
- Technical explanation of the 2006 Germany protocolhttps://www.irs.gov/pub/irs-trty/germanyte07.pdf
- Instructions for Form 8233https://www.irs.gov/instructions/i8233
- Claiming tax treaty benefitshttps://www.irs.gov/individuals/international-taxpayers/claiming-tax-treaty-benefits
Checked against IRS.gov on October 3, 2026. General information, not tax advice.